TL;DR

Get business pricing on office and shipping supplies
- Business-only prices and quantity discounts
- Tax-exempt purchasing
- Multiple users, one account, clear invoices
A Kiplinger personal-finance report advises parents to make financial help for adult children purposeful, clearly bounded and affordable for the parents. It recommends support that can build independence, such as career training or retirement contributions, while warning that ongoing lifestyle subsidies and unaffordable home purchases can create strain. The report does not provide new research or quantify the effects of these approaches.
Kiplinger has published guidance for parents giving money to adult children, urging them to set clear limits, fund goals that can build independence and avoid jeopardizing their own retirement. The report discusses choices including help with a home purchase, recurring living expenses and gifts for education or career development.
The report warns that financial assistance can become a burden if parents help a child take on costs they cannot manage independently. In a home purchase, for example, a parent’s contribution to a down payment or closing costs may help, but the child still needs to be able to handle ongoing expenses such as mortgage payments, maintenance and homeowners association fees. Kiplinger recommends considering a home within the child’s means or matching a down-payment contribution so the child also contributes.
Kiplinger also cautions against making an expensive lifestyle appear routine by regularly paying for rent, vacations or luxury purchases. It says parents can still choose to pay for an occasional family trip or other special expense, but should make clear that the spending is not an ongoing expectation. The report’s broader point is to distinguish a one-time gift from continuing support.
For adult children, the article suggests that help can be directed toward costs intended to support future independence, including professional certifications, business start-up funds or retirement-account contributions. It advises parents to discuss the purpose and limits of a gift in advance. If money is expected to be repaid, it recommends agreeing on repayment terms clearly rather than leaving the arrangement ambiguous.
Setting Limits on Family Support
Financial gifts can ease a child’s immediate costs and may shape expectations about future support. The report says that setting boundaries can help families distinguish temporary assistance from an ongoing commitment and clarify when payments will stop.
The report also notes that money used to support an adult child is no longer available for a parent’s own needs. Kiplinger warns that using retirement savings or funding expenses beyond a parent’s means could affect the parent’s long-term financial position. If a parent later needs financial support, the shortfall may also affect family members.
These are planning considerations, not a guarantee that any particular gift will produce independence or prevent financial strain. The report offers general guidance rather than individualized financial advice or evidence measuring the results of different kinds of family support.
As an affiliate, we earn on qualifying purchases.
From Childhood Gifts to Adult Costs
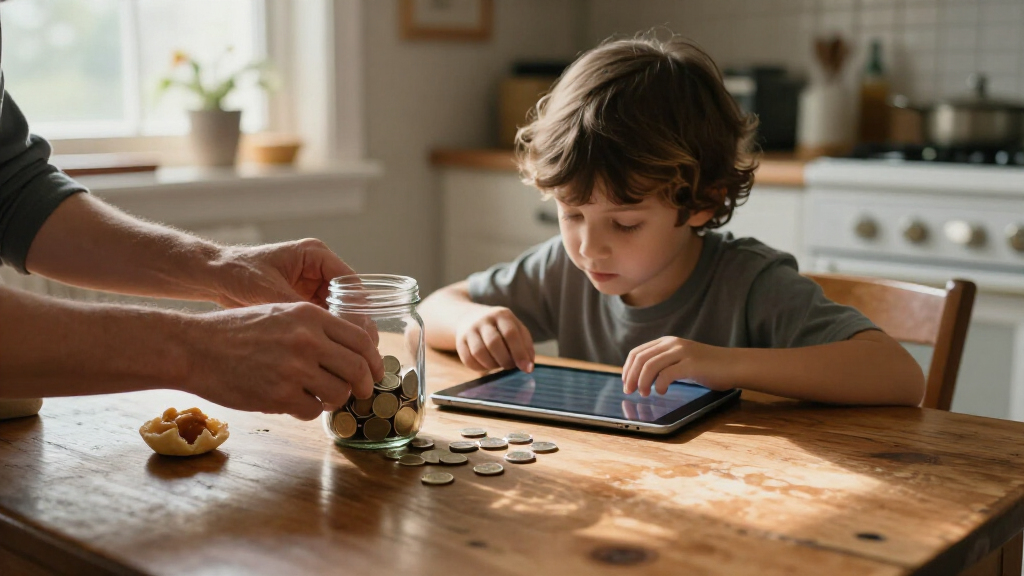
The article describes family financial support as a decision that can involve different costs as children grow. Support for adult children may include housing, tuition, rent or vacations. The distinction between a gift and a recurring subsidy is relevant when an adult child is making independent financial decisions.
Kiplinger cites a survey by mortgage lender Veterans United Home Loans, saying more than half of parents of adult children were willing to help their children buy a home. The supplied report does not give the survey’s sample size, field dates or question wording, so the figure should be read as a reported survey result rather than a complete measure of parents’ behavior.
The article recommends discussing expectations before money changes hands, including what the payment covers, whether it is one-time or recurring, who is responsible for costs such as taxes and maintenance, and whether repayment is expected. Those details can help families distinguish a gift from a loan or continuing financial commitment.
“The goal is empowerment, not entitlement.”
— Kiplinger report
professional certification study guides
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Limits of the Available Evidence
The supplied source is a personal-finance report, not a study testing whether its recommendations prevent financial dependence. It gives no outcome data on families who set spending limits, contribute to a home purchase or pay for career training. The Veterans United survey is summarized without its date, sample size or methodology, leaving the basis and scope of the reported figure unclear.
The article also does not set a specific dollar limit for gifts or provide a formula for deciding how much a parent can afford. What is suitable depends on individual circumstances, including a parent’s retirement needs and the child’s income and expenses. Those details are not assessed in the report.
home down payment assistance funds
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
What Families Should Discuss First
The report offers no scheduled follow-up or policy change. It recommends that parents discuss the purpose of financial help, whether it is one-time or ongoing, which costs remain the child’s responsibility and whether repayment is expected before committing money.
Parents considering substantial support can review how it fits their own budget and retirement plans before making a commitment. The source does not prescribe a particular financial product or individualized plan; it recommends that support be intentional, clearly explained and within the parent’s means.
financial planning books for parents
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Key Questions
What kinds of financial help does the report suggest?
Kiplinger points to support intended to build future capacity, such as paying for relevant professional certification, contributing seed money to a viable business or adding to a retirement account. It also says the help should fit the child’s interests and circumstances.
Should parents help adult children buy a home?
The report does not rule out help with a down payment or closing costs. It advises parents to consider whether the child can afford ongoing payments and expenses, and suggests buying within the child’s means or matching the child’s contribution.
How can parents avoid misunderstandings about a gift?
Explain what the money covers and whether it is a one-time payment or continuing support. For a loan, agree on repayment terms; for a home purchase, discuss responsibility for costs such as taxes and maintenance.
Why does the article warn about using retirement savings?
Kiplinger says reducing retirement resources to fund an adult child may leave the parent less financially secure later. It also notes that a parent who needs financial help in retirement could place pressure on the family in turn.
Source: rss
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.